Publish Date: August 11, 2026
Author: Seubert
Tags: Blog - SeubertU
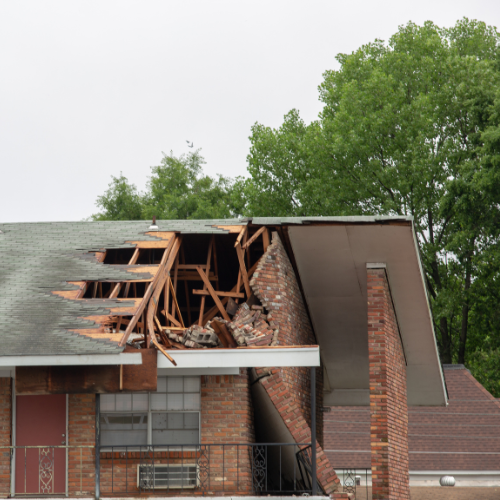
A fire, severe storm, burst pipe or other property loss can disrupt business operations in an instant. While the damage itself may be unavoidable, the actions taken during the first 24 hours can significantly influence the claims process and the speed of recovery. By responding promptly and documenting the situation carefully, businesses can help protect both their property and their insurance claim.
Prioritize Safety
Before entering a damaged building, ensure it is safe. Structural damage, gas leaks, electrical hazards or other dangerous conditions should be evaluated by emergency responders or utility providers before anyone enters the property. If the loss involves theft or vandalism, contact law enforcement immediately. A police report is often required when filing an insurance claim for these types of losses.
Notify Your Insurance Carrier
Commercial property policies generally require losses to be reported as soon as possible. Prompt notification allows the insurer to begin investigating the claim and assigning an adjuster.
When reporting the loss, be prepared with the following:
- Your policy number
- The date and time of the incident
- A brief description of what happened
Avoid estimating repair costs or speculating about the cause until professionals have completed their assessments. After calling the claims department, follow up with written notice and notify your insurance broker or agent, who can help guide you through the claims process.
Document the Damage
Before cleaning up or making repairs, thoroughly document the damage. Take photographs and videos of affected areas, equipment, inventory and structural damage. Time-stamped images provide valuable evidence during the claims process.
It is also important to:
- Preserve damaged property whenever possible until the adjuster has inspected it.
- Keep a written log of damage, conversations and actions taken.
- Gather pre-loss photos, inspection records and maintenance documentation.
- Save receipts for emergency repairs and mitigation expenses.
Good documentation often helps prevent disputes and supports a faster settlement.
Prevent Additional Damage
Insurance policies typically require policyholders to take reasonable steps to prevent further loss. Temporary measures may include boarding broken windows, tarping damaged roofs, shutting off utilities or removing standing water. These actions help reduce additional damage while preserving the property for inspection. Keep receipts for any emergency expenses, as these costs may be reimbursable under your policy.
Track Business Interruptions
If operations are interrupted, begin documenting the financial impact immediately. Record canceled orders, lost sales, extra operating expenses, and payroll impacts. Maintaining accurate financial records will help support any business income claim covered under your policy.
Your Risk Transfer Resource
Recovering from a commercial property loss begins long before disaster strikes. Working with knowledgeable insurance professionals can help your business understand its property coverage, strengthen loss control efforts and prepare for future incidents.
Contact us to see how you could minimize risk:
- Business Insurance|
Recent News
How AI Is Reshaping the Labor Market
Hiring patterns are changing, entry-level pipelines are thinning and the types of roles employers are actively seeking are moving.
Compliance Update: Allegheny County Advances Revised Paid Parental Leave Proposal
Allegheny County’s revised proposal would require up to 12 weeks of paid parental leave
Seubert Webinar Recap: Pharmacy Benefits Beyond the Rebate
Missed our pharmacy benefits webinar? Get the key takeaways on rebates, biosimilars, GLP-1 coverage, specialty drugs and PBM transparency, plus the recording.
Employee Spotlight: Gianna Mancino
Please join us in welcoming Gianna Mancino to the Seubert Team!
Zero-day Vulnerabilities Explained
A zero-day vulnerability may go undetected or otherwise unresolved for an extended period, quietly existing within an organization’s broader IT infrastructure without affecting typical operations.
Employee Spotlight: Dylan Ward
Please help us welcome Dylan Ward to the Seubert Team as a Surety Operations Specialist in our Surety Bond Division!