Publish Date: April 30, 2026
Author: Seubert
Tags: Blog - SeubertU
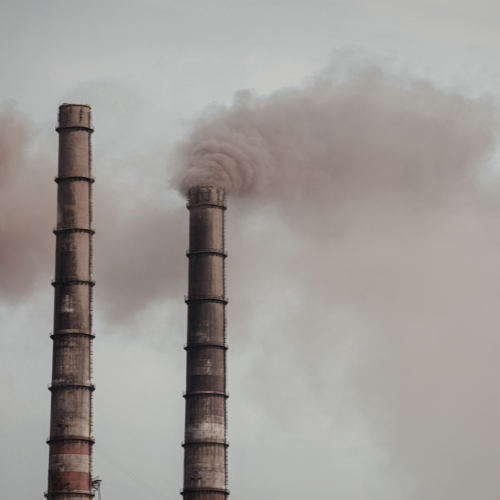
Environmental incidents can expose businesses to significant legal and financial liability. Pollution events may affect air, water, soil, and natural resources and create health risks if individuals are exposed to hazardous substances. Understanding environmental liability exposures can help organizations better manage these risks.
What Is Environmental Liability?
Environmental liability is commonly associated with chemical spills, hazardous waste, and industrial contamination, but its scope is much broader. Federal laws such as the Comprehensive Environmental Response, Compensation, and Liability Act, the Clean Water Act, and the Clean Air Act can impose liability for activities that harm air, water, or land.
For example, renovation work may disturb aging infrastructure and release contaminants, or severe weather could cause wastewater facilities to discharge pollutants into nearby waterways. Regardless of the cause, organizations may face significant financial consequences when environmental incidents occur. These costs may include regulatory fines, cleanup and remediation expenses, operational disruptions, and legal claims. Businesses may also face liability for third-party damages, including bodily injury, illness, or property damage linked to contamination.
Common Sources of Environmental Liability Exposures
Environmental liability exposures can arise suddenly or develop over time. Some common sources include the following:
- Operational activities—Routine operations may release pollutants through emissions, spills, equipment failures, or improper waste handling.
- Property issues—Hidden hazards such as underground storage tanks, historic contamination, asbestos, or lead paint can create liabilities during property transactions or site assessments.
- Supply chain risks—Pollution incidents involving suppliers, distributors, or transportation partners may create liability if contracts lack environmental protections.
- Regulatory enforcement—Noncompliance with environmental laws may lead to fines, enforcement actions, or lawsuits from regulators or affected third parties.
Financial and Operational Impacts
Environmental liability incidents can create significant financial and operational challenges for organizations.
Cleanup and remediation efforts often require site investigations, contaminant removal, and ongoing monitoring. Pollution events may also trigger operational shutdowns, supply chain disruptions, and reputational damage. In addition, legal costs related to regulatory enforcement or third-party claims can compound losses and may even exceed initial remediation expenses.
Managing Environmental Liability Exposures
Organizations can take several steps to help reduce environmental liability risks:
- Implement compliance programs. Review environmental obligations regularly, conduct audits, and train employees on proper waste handling and spill response procedures.
- Conduct due diligence. Evaluate environmental risks during property transactions, supplier relationships, and development projects.
- Review insurance coverage. Standard commercial property and general liability policies often exclude pollution-related losses, making environmental liability coverage an important consideration.
Environmental liability exposures can arise from many sources, making proactive risk management and appropriate insurance coverage essential for protecting business operations.
Contact us to see how you could minimize risk:
- Business Insurance|
Recent News
IRS Announces Health Plan Affordability Percentage for 2027
The IRS released Revenue Procedure 2026-26 to index the contribution percentage in 2027 for determining the affordability of an employer’s health plan under the ACA.
IRS Releases Pay-or-Play Affordability Percentage for 2027
For plan years beginning in 2027, employer-sponsored coverage will be considered affordable under the ACA’s “pay-or-play” rules if the employee’s required contribution for self-only coverage does not exceed 10.22% of their household income for the year.
Basic Loss Control Techniques
The world will never be free of cyber risks, but there are many loss control techniques you can implement to help protect your business from exposures.
2026 Struttin’ Our Stuffin’ Turkey Trot
2026 Struttin’ Our Stuffin’ Turkey TrotType In-PersonDate November 26, 2026Location North Park, Allison Park2026 Struttin’ Our Stuffin’ Turkey TrotRegistration is open for the tenth annual Seubert Struttin’ Our Stuffin’ Turkey Trot. Join us on Thanksgiving morning, Thursday, November 26, 2026, at the North Park Rose Barn and Boathouse in Allison Park. Whether you are chasing a personal best or just
Hiring the Right Drivers: Building a Safer Fleet From the Start
Careful recruiting and screening help build a safer, more reliable workforce.
Weather Preparedness Around the Year: Real-World Strategies for Construction and Transportation Businesses
Learn seasonal weather preparedness strategies that help construction and transportation businesses reduce claims, speed recovery, and stabilize premiums.