Publish Date: September 17, 2026
Author: Seubert
Tags: Blog - SeubertU
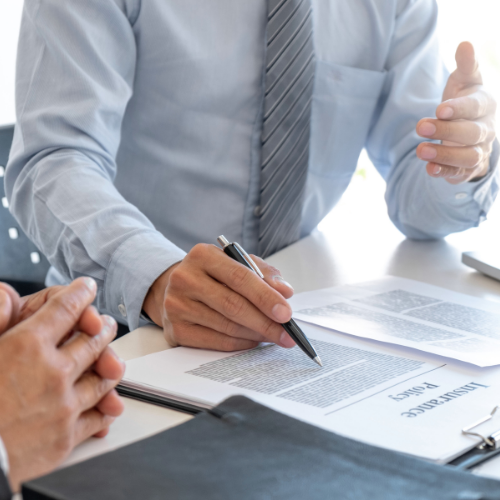
When businesses purchase commercial insurance, they often focus on limits, deductibles and policy terms. Yet the insurance application is equally important. It is a legal document insurers use to evaluate risk, determine eligibility and establish coverage terms and pricing. Errors or omissions can create serious problems when a claim arises.
Why the Application Matters
An application provides details about operations, revenue, locations, claims history and safety practices. This information forms the underwriting foundation of the policy. Many commercial policies contain concealment, misrepresentation or fraud provisions that may allow an insurer to deny a claim or void coverage when material information is inaccurate or omitted.
A misrepresentation is material when accurate information would have influenced the insurer’s decision to offer coverage or changed the premium, limits or terms. Depending on the circumstances, policy language and applicable state law, the insurer may deny a related claim, rescind the policy as though it never existed or seek to reform the policy to reflect the terms it would have issued. Intent to deceive is not always required; in some jurisdictions, even an honest mistake can have significant consequences.
Common Application Errors
Several mistakes can increase coverage risk:
- Incomplete operations descriptions—Vague or outdated descriptions may omit specialized services or activities the insurer was never asked to underwrite.
- Undisclosed locations—Every location where a business operates, stores property or performs work should be reported, including secondary or temporary sites.
- Incorrectly named insureds—The application should identify the legal entity that owns or operates the business and bears the risk. Using a trade name, parent company or other incorrect entity may create gaps.
These are only examples. Any information that could influence underwriting, pricing or policy terms may be material. A complete, accurate disclosure gives the insurer a clear picture of the risk and can place the business in a stronger position if a dispute occurs.
When a question is unclear, applicants should seek clarification rather than estimate or leave the response incomplete. Supporting records can also help demonstrate what information was disclosed and when.
Give Renewals the Same Attention
Renewal is not simply an automatic continuation of existing coverage. The insurer underwrites the risk again using the renewal application. Prefilled information from prior years may no longer reflect current operations. Businesses should review every renewal carefully and update changes involving services, revenue, ownership, locations or organizational structure.
To reduce application-related risks, businesses should:
- Treat each application as a legal document and have someone familiar with current operations review it before signing.
- Record operational changes throughout the year and discuss them with the insurance professional before renewal.
- Request a copy of the submitted application and compare it with current operations.
- Work with an insurance professional who asks detailed questions about the business, not merely its existing coverage.
The insurance application is the foundation of the coverage relationship. Accurate, current information can help businesses avoid disputes and ensure their policies respond as intended.
Contact us to see how you could minimize risk:
- Business Insurance|
Recent News
How Commercial Insurance Applications Affect Your Coverage
When businesses purchase commercial insurance, they often focus on limits, deductibles and policy terms. Yet the insurance application is equally important. It is a legal document insurers use to evaluate risk, determine eligibility and establish coverage terms and pricing.
Seubert Celebrates 10 Years on Pittsburgh’s North Shore
Seubert & Associates celebrates 10 years at its Pittsburgh North Shore headquarters with a look at its growth and newly renovated office.
Employee Spotlight: Mariah Gigler
Please join us in welcoming Mariah Gigler to the Seubert Team!
DOL Proposes to Expand Electronic Delivery Options for Group Health Plans
On July 23, 2026, the U.S. DOL issued a proposed rule that would establish a new, additional safe harbor for group health plan administrators to use electronic media to furnish plan disclosures required under the ERISA.
Employee Spotlight: Delany Graff
Please join us in welcoming Delany Graff to Seubert’s Admin Department as an Accounting Clerk!
Compliance Update: Federal Agencies Issue FAQs Addressing Key Issues in Health Plan Tobacco Surcharge Lawsuits
Federal agencies have issued new FAQ guidance addressing two issues at the center of tobacco surcharge class-action lawsuits: when the full wellness program reward must be provided, and what employee notice is required. Here’s what employers need to know.