Image
Publish Date: May 6, 2024
Author: Seubert
Tags: Blog - SeubertU

The Impact of Roof Age on Commercial Property Insurance

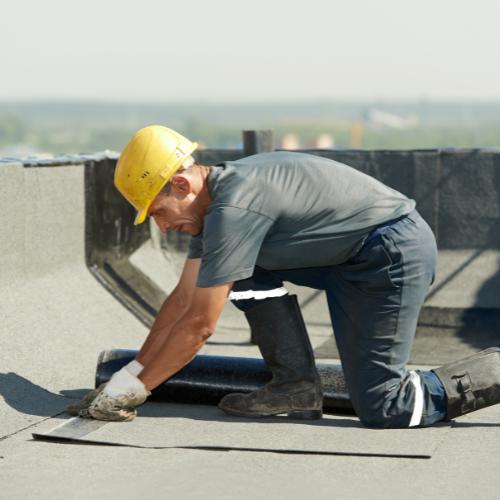
A commercial property’s roof plays a significant role in preserving the building’s structural integrity and protecting it from various weather exposures. As a roof ages, it becomes weaker and increasingly vulnerable to failure. Additionally, older roofs may be more prone to coverage exclusions in insurance policies and could contribute to denied claims when losses occur. To avoid such issues with insurance, property owners must maintain their roofs and provide proper information to insurers.

Based on average roof age data, most commercial property insurers either limit or fully exclude coverage for buildings with roofs over 20 years old, as older roofs are more likely to have issues (e.g., cracks, sagging areas, leaks) and be more susceptible to large-scale damage or collapse. These exposures are key factors influencing premium rates or whether the building will receive coverage.

Providing incorrect roof age data (intentionally or unintentionally) about a roof’s age will likely lead to inaccurate risk assessments during the underwriting process and skew premium calculations. It can create misalignment between building owners and insurers, causing increased tension during the claims process. For example, when building owners encounter property losses involving older roofs, insurers will discover they were provided incorrect roof age data and likely deny the associated claims. If inaccurate data was knowingly provided, this may also amount to fraud and lead to being dropped by an insurer. Furthermore, insurers will adjust building owners’ risk levels and premium calculations based on updated roof age data, potentially resulting in higher rates or additional coverage limitations.

Even when providing accurate roof age data, building owners should be aware of possible coverage complications with claims that involve older roofs. For instance, building owners with policies that offer actual cash value (ACV) coverage could be left with considerable out-of-pocket costs if losses require the replacement of their older roofs. This is because ACV coverage relies on the depreciated value of the affected property or structure when providing a payout. In addition, older roofs may be non-compliant with the latest building codes; not all insurers provide coverage for building code upgrades, which may be required if the roof needs to be repaired or replaced. This coverage gap could further exacerbate out-of-pocket costs. Considering the impact of roof age on commercial property insurance, building owners with older roofs should take action to reduce their risks. Here are some best practices for property owners to keep in mind:

  • Conduct regular maintenance and repairs. This can prolong the lifespan of older roofs and preserve their structural integrity. Property owners should also consider including periodic building code upgrades in their maintenance plans.
  • Provide accurate documentation. This allows underwriters to conduct accurate calculations and prevents misalignment with insurers. This documentation should include roof maintenance schedules, repair records, and, above all, accurate age data.
  • Ensure proper coverage. Building owners should work with insurance professionals to review their policies, determine their specific coverage needs, and secure a policy that provides adequate protection against potential financial losses.

Being aware of an old roof’s impact on commercial property insurance can help business owners take appropriate action to address associated exposures.

Contact us to see how you could minimize risk:

Recent News

IRS Announces Health Plan Affordability Percentage for 2027

The IRS released Revenue Procedure 2026-26 to index the contribution percentage in 2027 for determining the affordability of an employer’s health plan under the ACA.

IRS Releases Pay-or-Play Affordability Percentage for 2027

For plan years beginning in 2027, employer-sponsored coverage will be considered affordable under the ACA’s “pay-or-play” rules if the employee’s required contribution for self-only coverage does not exceed 10.22% of their household income for the year.

Basic Loss Control Techniques

The world will never be free of cyber risks, but there are many loss control techniques you can implement to help protect your business from exposures.

2026 Struttin’ Our Stuffin’ Turkey Trot

2026 Struttin’ Our Stuffin’ Turkey TrotType In-PersonDate November 26, 2026Location North Park, Allison Park2026 Struttin’ Our Stuffin’ Turkey TrotRegistration is open for the tenth annual Seubert Struttin’ Our Stuffin’ Turkey Trot. Join us on Thanksgiving morning, Thursday, November 26, 2026, at the North Park Rose Barn and Boathouse in Allison Park. Whether you are chasing a personal best or just

Hiring the Right Drivers: Building a Safer Fleet From the Start

Careful recruiting and screening help build a safer, more reliable workforce.

Weather Preparedness Around the Year: Real-World Strategies for Construction and Transportation Businesses

Learn seasonal weather preparedness strategies that help construction and transportation businesses reduce claims, speed recovery, and stabilize premiums.